What is money lending? Explanation of the definition in the Money Lending Business Act and procedures for money lenders
Updated: July 2026, 8
The moneylending business refers to the business of lending money or acting as an intermediary for such transactions. While it's often associated with consumer finance companies, it's crucial to understand the differences between banks and other financial institutions, as well as their mechanisms and rules. In Japan, the Moneylending Business Act imposes strict restrictions and standards, and it's illegal to conduct moneylending without meeting certain requirements and obtaining the appropriate registration. Operating a moneylending business without registration is illegal.
This page provides a simple and easy-to-understand explanation of the basic meaning and definition of moneylending, what kinds of operations fall under this category, and what is required for registration, including what you can do and how it works.
Definition of money lending business
- Money lending or money lending intermediation business
- Intermediary business for the delivery or receipt of money through discounting bills, selling security, or other similar methods
*Excluding those for which specialized laws have been enacted, such as banks, trusts, and insurance companies, the term "lending business" refers to the business of lending money or acting as an intermediary for lending money.
According to the Money Lending Business Act, money lending is defined as "the business of lending money or acting as an intermediary in the lending and borrowing of money."
"Conducting it as a business" refers to "the act of lending money to an unspecified or large number of people with the intention of doing so repeatedly and continuously, and receiving interest or a similar benefit."
Therefore, the mere act of lending money does not constitute money lending business.
Based on this definition, we will explain in detail below the cases that fall under the category of money lending business and the cases that are excluded from money lending business.
What kind of business actually falls under the money lending industry?
Cases that fall under the category of money lending business
Under the Money Lending Business Act, activities that constitute money lending are determined based on whether they are provided as part of the company's services.
Cash advances and card loans offered by non-bank financial institutions such as consumer finance companies, credit card companies, and credit sales companies are lending services that are regulated under the Money Lending Business Act.
Notable examples
① Consumer finance company
② Bill discount agent
③Business finance companies (real estate collateral finance companies, etc.)
④Card companies and credit companies that provide loans
⑤Department stores and supermarkets that provide loans
Cases where businesses are excluded from the money lending business
On the other hand, the following four entities lend money as a business but do not qualify as moneylending businesses.
①Implemented by the national or local government
Living welfare fund loan systems run by the prefectural social welfare councils, etc. Loan systems run by the national and prefectural governments are not considered money lending businesses.
②Those conducted by banks, etc.
Bank card loans. Services provided by banks are subject to the Banking Act.
③ What an employer does for its employees
Employee loan system. This is introduced as an employee benefit in some companies and is also called an in-house loan system or in-house financing.
④ Anything that is incidental to a transaction by an entity engaged in the business of buying and selling, transporting, storing, or acting as an intermediary in the buying and selling of goods.
This includes acting as an intermediary to financial institutions and loan companies in the case of home loans and car loans.
How can I start a money lending business?
To operate a money lending business, you must be registered with the national or prefectural government.
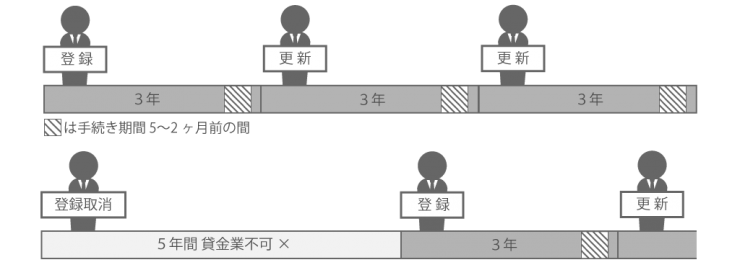
The validity period is 3 years.
In addition, you must complete the registration renewal procedure between 5 months and 2 months before the expiration date.
Registration is not available for adult wards, persons under curatorship, persons whose registration has been revoked for less than five years, and those who have received a sentence of imprisonment or more.
You can check whether a company is a registered money lender by using the "Registered Money Lender Information Search Service" available on the Financial Services Agency's website.
Moneylenders registered with the Director-General of the Regional Financial Bureau can be found on the "List of Licensed, Authorized, Registered, etc. Companies" published on the Financial Services Agency website.
Registered money lender
The place to apply for registration as a money lending business varies depending on the location of your business office.
① If all business offices or offices are located within one prefecture ⇒ Registered by the prefectural governor
② If the business office or office is located in two or more prefectures ⇒ Registered with the Director of the National Finance Bureau
*In the case of ②, the person to be registered is the Director-General of the Finance Bureau who has jurisdiction over the area where the main business office, etc. is located.
(Example: If you have offices in Kanagawa Prefecture and Tokyo, you will be the Director of the Kanto Local Finance Bureau)
Information to be included in the registration application form
When registering as a money lender, you will need to complete and submit a registration application.
Specifically, you need to fill in the following:
- Business name or name and address
- In the case of a corporation, the names of its directors
- In the case of an individual, if there are employees as specified by government ordinance, their names
- Name and address of the business office
- Name and registration number of the money lending business manager at the office
- Telephone numbers and contact details of business offices, etc. displayed when advertising or soliciting
- Type and method of business
- If you have other businesses, what type of business do you have?
Key requirements and points to note for money lending business
To operate as a money lender, a company must meet the following requirements:
① Appointment of a money lending business manager
A money lending business manager must be appointed to each office (at least 50/XNUMX of the number of people engaged in money lending business).
A money lending business manager is someone who has passed the Money Lending Business Manager Qualification Examination (national examination) and completed manager registration.
②Net asset requirement
The net assets must be more than 5,000 million yen.
This amount must not fall below the limit during the period in which the money lending business is conducted.
3) Securing experienced executives and employees
Having directors and employees with experience in lending operations that meet certain conditions.
<For corporations>
・One of the directors must have at least three years of experience in lending operations.
<For individuals>
One of the following conditions must be met:
- The applicant must have more than three years of experience in lending operations.
Each office must have at least one full-time officer or employee who has been engaged in lending operations for more than one year.
You cannot start a money lending business unless you have at least three years of experience working in a bank or consumer finance company.
Even if the company is a corporation, it must have at least one director with three years or more of work experience.
④ Contract with Designated Dispute Resolution Organizer (ADR)
A basic agreement on proceedings must be concluded with an ADR institution.
The Japan Finance Association is a major one.
⑤Subscription to a designated credit information agency
Join a designated credit bureau.
★What is a designated credit information agency?
Designated credit bureaus are organizations to which moneylenders and financial institutions belong and which share borrowers' credit information.
This information includes your loan balance, repayment history, and past due information.
<Major designated credit information agencies>
・Japan Credit Information Center (JICC)
・CIC Corporation
<The role of designated credit bureaus>
①Collection and provision of credit information
We centrally manage credit information provided by moneylenders and financial institutions and provide it to our member companies.
This allows lenders to get a quick and accurate picture of a borrower's credit standing.
2) Reducing lending risks
By using the borrower's credit information, we reduce the risks of lending and prevent bad loans from occurring.
Proper credit assessment helps lenders avoid making risky loans.
3) Support for proper business operations
By sharing credit information, we will support moneylenders and other such businesses in conducting their business appropriately.
This will help maintain the health of the entire industry.
⑥Not falling under any item of Article 6, Paragraph 1 of the Money Lending Business Act
Article 6, Paragraph 1 of the Money Lending Business Act stipulates the conditions under which a company will not be recognized as a money lender.
- Those who have difficulty with perception, judgment, and communication and are unable to carry out their duties.
- Within five years of being sentenced to imprisonment or more (including the expiration of a suspended sentence).
- Those who belong to anti-social forces such as gang members.
- Any other person who is likely to commit fraudulent or dishonest acts in relation to the money lending business.
Cases where a moneylender's registration expires
A moneylender's registration may lapse under certain conditions.
For example, if facts that constitute grounds for cancellation of registration are discovered after registration, or if renewal procedures are neglected.
If your registration expires, you will need to re-register.
The validity period of registration for money lending business is three years.
If you wish to continue operating as a money lender after the expiration of the validity period, you must complete the renewal procedure at least two months before the expiration of the validity period.
A moneylender's registration will lapse in the following cases, including if the renewal procedure is not completed.
1. When someone dies
If the lender is an individual, the registration will expire upon the lender's death.
② When a corporation is dissolved through a merger
If a corporation ceases to exist as a result of the merger, its registration will lapse.
3) When a decision is made to commence bankruptcy proceedings.
If a lender receives a decision to commence bankruptcy proceedings, its registration will lapse at that point.
④ When a corporation is dissolved or ceases money lending business
If the corporation is dissolved or ceases its money lending business, its registration will lapse.
⑤ When you do not receive a renewal of your registration
If you do not complete the renewal procedure two months prior to the expiration date, your registration will expire at that point.
⑥When a new registration is received
This is when you lapse your existing registration and get a new one.
⑦ When there are other legal reasons for invalidation
In addition, registration may lapse for certain reasons under the Money Lending Business Act.
For inquiries regarding money lending, please contact Support Administrative Scrivener Corporation
At Support Administrative Scrivener Corporation, we provide application support and consulting regarding the Money Lending Business Act to all new and existing money lenders.
Our strengths are our speed and appropriate leadership ability, which comes from sharing our wealth of experience and know-how with a small group of elite people.
If you are having trouble with the money lending business, such as ``I'm thinking about registering, but I don't know how long it will take and what preparations I need to make,'' or ``I don't know what to do regarding legal management,'' please feel free to contact us. Please contact us.
Person in charge: Keiko Watanabe