There was a time when the social lending (lending-type/loan-type crowdfunding) business was affected by scandals and other factors that caused doubts about its credibility. However, since then, progress has been made in establishing legal regulations and implementing them in practice, and the business continues to attract attention as an attractive investment scheme. We receive many inquiries from people interested in entering this field.
This page explains social lending (lending-type/loan-type crowdfunding).
■ Overview
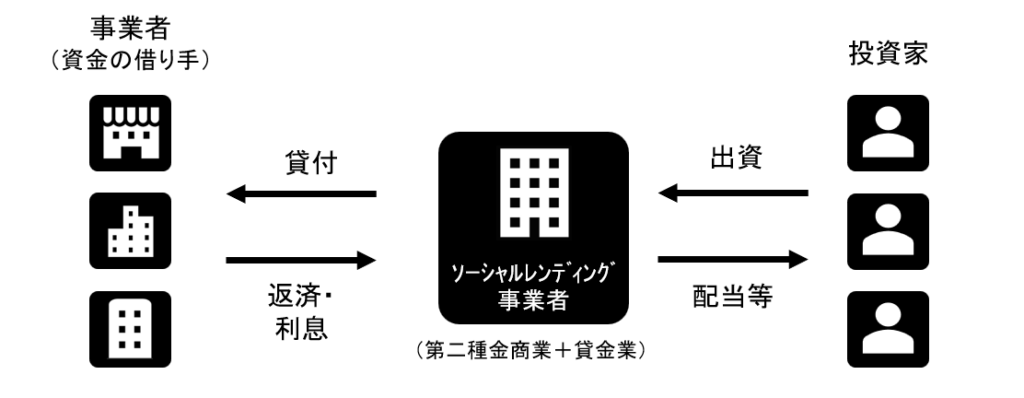
Social lending is also known as "lending-type/loan-type crowdfunding" and is basically a system in which social lending operators (※) that are registered as Type II Financial Instruments Business Operators (fund classification) and money lending businesses lend money (money consumption loans) to businesses (borrowers seeking funds) using capital contributions raised from investors.
(*) There are cases where the money lending business is acquired through a "subsidiary" other than the financial institution.
Social lending operators match "borrowers (businesses) seeking to raise funds" with "investors wanting to invest" through online platforms, etc. This allows "borrowers wishing to raise funds" to raise funds as loans, and "investors who want to invest" to contribute (invest) in a fund and receive distribution of the profits.
There was a time when there were concerns about the creditworthiness of social lending, as it tends to target borrowers and businesses that have difficulty obtaining bank loans, and there have been scandals involving businesses involved. However, since then, the legal regulations and interpretations regarding social lending businesses have been improved, and it seems that social lending continues to attract attention as an attractive investment product, as it is possible to invest with small amounts of money and there are many products with relatively high yields.
In fact, we often receive inquiries from companies looking to enter the social lending business.
■ Scheme explanation
There are various schemes within social lending. Please note that the types of licenses and permits required and the entity that obtains them will vary depending on the scheme.
Here we will introduce some common social lending schemes.
In addition, in the social lending business, when collecting funds from investors, it is common to enter into a silent partnership agreement with the investor and raise funds (such as self-offering of collective investment scheme interests), and then use the raised funds as capital to provide loans (lending). The following is based on this case.
[Case 1: A case where a social lending business operator solicits and lends funds by itself]
This is a scheme in which the social lending operator itself acts as the fund operator (the operator of a silent partnership agreement as provided for in Article 535 of the Commercial Code), solicits funds from investors, and then uses the capital contributions solicited to provide loans (lending) to businesses (borrowers).
In this case, as a general rule, social lending operators are required to register as a Type II Financial Instruments Business (Fund Classification) for the solicitation of investors, and as a Money Lending Business for the lending of funds.
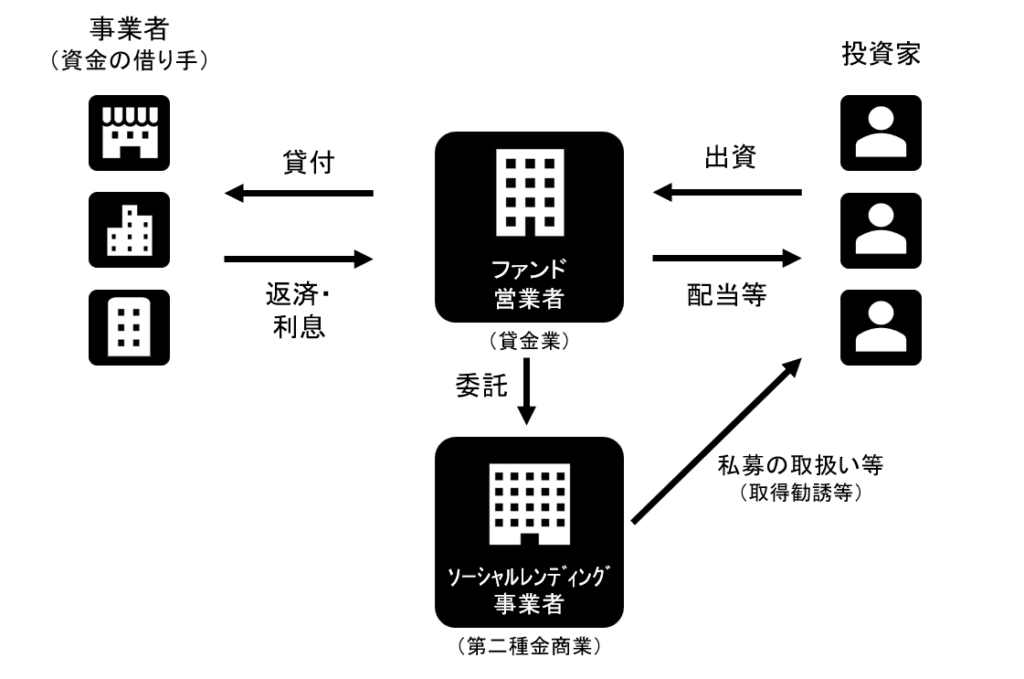
[Case 2: A social lending business operator only solicits funds]
This is a scheme in which the fund operator (the operator of a silent partnership agreement as defined in Article 535 of the Commercial Code) lends funds, and the act of soliciting investors is entrusted to a social lending business operator.
In this case, as a general rule, the fund operator (the operator of the anonymous partnership agreement prescribed in Article 535 of the Commercial Code) will register as a money lending business for the act of lending funds, and the social lending operator will register as a Type II Financial Instruments Business (fund classification) for the act of soliciting investors on behalf of the operator (handling private placements, etc.).
In this scheme, the act of social lending business operators soliciting investors online (handling private placements) falls under the category of "electronic offering handling business" under the Financial Instruments and Exchange Act, and the requirements are more stringent than for regular Type II financial instruments business (without electronic offering handling business). (Please note that with the amendment to the law that will come into effect on November 2024, 11, this will now newly fall under electronic offering handling business.)
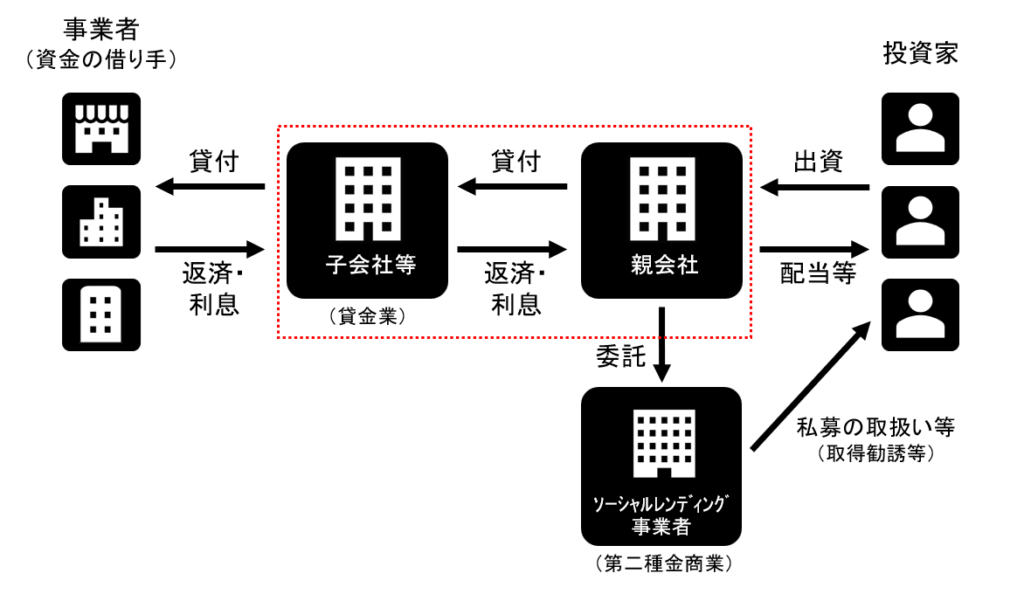
[Case 3: Other cases]
As another example, we will introduce a case where a large number of people are involved.
In the social lending business, there are cases where operational tasks are divided up within the group due to strategic considerations regarding permits and licenses and applicable regulations. For example, by "deliberating" to have Type 2 financial business and money lending businesses held in separate companies, a company may aim to improve its expertise in its respective fields and to enhance compliance and management by thoroughly managing information.
In the above scheme, the "parent company" lends to the "subsidiary." However, since loans between group companies are generally exempt from the money lending regulations, registration as a money lender is not required.
■ Issues surrounding social lending
(1) Anonymity and multiple borrowers
As a premise, the Money Lending Business Act requires that a lender register as a money lender if it "supplies the funds necessary for lending to a specific borrower" and "makes the decision to extend the loan."
In the case of social lending, in order to avoid being judged as "essentially engaging in lending activities, which means that registration as a money lending business is necessary" with regard to "investors who provide funds," the following measures have traditionally been taken in sales solicitations:
Borrower "anonymization" No information that could identify the borrower is disclosed
Diversification of Borrowers It is a scheme to provide funds to multiple borrowers
In other words, by not specifying the borrowers (anonymization) and providing funds to multiple borrowers (multiple borrowers), it is concluded that "it cannot be said that the investor is engaging in lending activities (= registration as a money lending business is not required)." However, this approach of anonymizing and diversifying borrowers had problems, such as an unclear legal basis and concerns about investor protection because the investment targets were not made public.
(2) Options other than anonymization and multiple data
In 2019 and 2023, the Financial Services Agency presented "options other than anonymization and multitude" for the practical implementation of this "anonymization and multitude of borrowers" through its no-action letter pre-confirmation procedure on the applicability of laws and regulations.
In other words, investors can avoid registering as money lenders without having to be anonymized or multiple. Specifically, if the following measures are taken, investors are not making the decision to extend the loan, and registration as a money lending business is no longer required.
■ In the case of anonymous partnership contract scheme (Reference:Reply dated March 2019, 31(Summary below)
①Business scheme etc.
The borrower is a "corporation" and the fund is a loan-type fund.
The scheme is an anonymous partnership agreement as stipulated in Article 535 of the Commercial Code.
The provider of the funds (investor) cannot carry out lending operations and has no rights or obligations regarding the lending act.
② Fund operator (loan provider)
In the loan agreement, the fund operator (loan provider) sets the loan conditions and presents them to the borrower.
It clearly states that the borrower and the investor will not have contact regarding the loan and the measures to ensure that such contact is not allowed
The fund operator (loan provider) must stipulate in its internal rules, as provided for in Article 24-6-12, Paragraph 2 of the Money Lending Business Act, measures to ensure that borrowers and investors do not have contact regarding loans.
③Fund distributor
The anonymous partnership agreement clearly states that the investor cannot carry out lending operations and has no rights or obligations regarding lending activities, and that there is no contact between the investor and the borrower regarding the loan, and there are measures to ensure that such contact is not allowed.
Fund distributors must inform investors that borrowers are prohibited from contacting investors regarding loans.
However, regardless of the above measures, if an investor and a borrower have contact regarding lending, it should be noted that the investor may be deemed to be engaging in lending activities and may be in violation of the Money Lending Business Act.
■In the case of an investment limited partnership agreement scheme (Reference:Reply dated June 2023, 5(Summary below)
①Business scheme etc.
The scheme must be based on an investment limited partnership agreement as stipulated in the Investment Limited Partnership Act.
The investor is a limited partner under the Investment Limited Partnership Law, has no disposition authority over the loan receivables, cannot carry out the lending business, and has no obligations with respect to the lending act, except for the liability to repay the partnership's debts up to the amount of the investor's contribution as provided for in Article 9, Paragraph 2 of the Investment Limited Partnership Law.
② Fund operator (loan provider)
The loan terms and conditions must clearly state that the fund operator (loan provider) will set the loan conditions and present them to the borrower, and that there will be no contact between the borrower and the investor regarding the loan, and that measures will be taken to ensure that such contact is not allowed.
The fund operator (loan provider) must stipulate in its internal rules, as provided for in Article 24-6-12, Paragraph 2 of the Money Lending Business Act, measures to ensure that borrowers and investors do not have contact regarding loans.
③Fund distributor
In the investment limited partnership agreement, etc., it is clearly stated that the investor has no disposition authority over the loan receivables, cannot execute the lending business, and has no obligations with respect to the lending act except for the liability to repay the partnership's debts up to the amount of the investor's investment as stipulated in Article 9, Paragraph 2 of the Investment Limited Partnership Act, and that the investor and the borrower will not have contact regarding the loan and measures to ensure that such contact is not allowed.
Fund distributors must inform investors that borrowers are prohibited from contacting investors regarding loans.
However, regardless of the above measures, if an investor and a borrower have contact regarding lending, it should be noted that the investor may be deemed to be engaging in lending activities and may be in violation of the Money Lending Business Act.
■ Legal reforms related to loan-type funds/social lending
The main legal changes that will affect loan-type funds/social lending businesses include the following, which will come into effect on November 2024, 11, due to the amendments to the Financial Instruments and Exchange Act:
① A new definition of "lending business rights" has been established. ② The exemption provisions for electronic solicitation handling business have been abolished. 3) The new definition of "electronic recruitment services"
In conjunction with this amendment to the law, each association's self-regulatory rules, Q&As, etc. have also been revised simultaneously. We will explain the key points by focusing on the changes before and after each revision.
① A new definition of "lending business rights" has been established.
[Before amendment]
Previously, in the case of loan-type funds (funds whose investment business is primarily the lending of money; same below), the "lending activity" which corresponds to the management portion of the fund was subject to the Money Lending Business Act rather than the Financial Instruments and Exchange Act. As a result, the managers of loan-type funds were not subject to the Financial Instruments and Exchange Act (they were not required to register as investment management businesses), and the "obligation to submit management reports" which is normally required of investment management companies also did not apply to them.
[After amendment]
The Financial Instruments and Exchange Act has newly defined the term "lending business rights, etc." The specific definitions are as follows:
Among the rights listed in Article 2, Paragraph 2, Items 3 to 6 of the FIEA, those in which the invested business related to the right (meaning a business conducted using money or other assets invested or contributed by the holder of the right) is a business that mainly involves lending money or other rights as specified by government ordinance (Article 29-2, Paragraph 1, Item 10 of the FIEA)
For example, if the business in which collective investment scheme interests are invested is a "business that primarily engages in the lending of money" or a "business that primarily engages in the acquisition of loan receivables," the right in question will fall under the category of a lending business right.
Not only rights related to so-called lending funds and lending crowdfunding businesses (collective investment scheme interests), but also rights related to loan receivables and factoring business funds (collective investment scheme interests) will fall under the newly established "lending business, etc. rights."
In addition, new provisions have been established prohibiting the sale and purchase of "lending business rights, etc."
Regarding "loan business rights," a new provision has been added that requires financial institutions, etc. that sell such rights to only handle rights that are contractually guaranteed to provide investors with appropriate information on a regular basis on the status of the investment target business related to the rights (Financial Instruments and Exchange Act, Article 40-3-3/Cabinet Office Ordinance, Article 125-2).
Similarly, a new provision has been established that prohibits the public offering, etc. of the rights to the loan business, etc. while knowing that the information that should be provided pursuant to the above contracts, etc. has not been provided (Article 40-3-4 of the Financial Instruments and Exchange Act).
These regulations are not limited to crowdfunding businesses alone, and they do not include exemptions for investors who are designated investors. In the future, businesses involved in the sale of loan business rights, etc., regardless of investor classification (special investor, etc.), will be required to verify the contents of contracts and the status of performance of obligations before conducting sales, etc., and will be required to keep evidence of this in practice.
② The exemption provisions for electronic solicitation handling business have been abolished.
[Before amendment]
The premise is that when private placements of certain securities (such as collective investment scheme interests) are handled by electronic means, this falls under "electronic offering handling business" and requires stricter business management and internal control systems. However, "collective investment scheme interests in which more than 50% of the investment amount is allocated to money lending business" are exempt from this rule.
In other words, loan-based crowdfunding is not subject to the regulations governing electronic solicitation operations, and is not required to establish the strict systems that would be required if it were considered to be an electronic solicitation operation.
[After amendment]
This amendment to the law has removed the exemption provisions.
In other words, after the revision of the law, in order to operate a loan-based crowdfunding business, it will fall under the category of "electronic solicitation handling business" and will be required to establish stricter business management and internal control systems.
* Strictly speaking, you will also need to consider whether your application falls under the newly established "electronic recruitment business" (see below).
Please note that if a person who has been conducting electronic solicitation or electronic solicitation handling operations for loan business rights, etc., before the enforcement date of the revised law intends to continue such operations after the revision, he/she will be required to "register changes within six months from the date of the revision" as a transitional measure.
3) The new definition of "electronic recruitment services"
[Before amendment]
A legal amendment effective on May 27, 5 created the new term "electronic offering handling operations." This means that operations involving the handling of private placements of certain securities by making them available for viewing on the financial instruments business operator's website, or by sending information via e-mail or other means, are deemed to be "electronic offering handling operations." This has required the establishment of stricter operational and internal control systems.
The activities covered by "electronic offering handling services" were limited to "handling of public offerings and private placements of securities" (≒ sales of securities conducted by a third party) as set forth in Article 2, Paragraph 8, Item 9 of the Financial Instruments and Exchange Act. Therefore, self-offerings in which the issuer of securities itself makes an offering were not covered by electronic offering handling services.
[After amendment]
With this amendment to the law, a new category of "electronic recruitment business" has been created in addition to the previous "electronic recruitment handling business."
The new "electronic solicitation business" covers "the acts set out in Article 2, Paragraph 8, Items 7 and 8," but excludes "acts other than acts related to lending business rights, etc." from the covered acts (Article 15-4-2 of the Enforcement Order).
In other words, when "acts related to lending business rights, etc." under "Article 2, Paragraph 8, Item 7: Public offering and private placement (self-offering)" and "Article 2, Paragraph 8, Item 8: Secondary offering and solicitation of sales to specified investors, etc." are conducted for certain securities by making them available for viewing on the financial instruments business operator's website, this will be considered an "electronic offering business," and the establishment of stricter business management and internal control systems will be required, just like the previous "electronic offering handling business."
Since "acts 'other' than those related to lending business rights" are not subject to electronic offering operations, private placements of business-type funds other than lending-type funds are not subject to the regulations on electronic offering operations, just as they were before the amendment.
In addition, when conducting the previous "electronic offering handling business" or the newly established "electronic offering business," it is necessary to comply with the special provisions set out in Article 43-5 of the FIEA and Article 146-2 of the Cabinet Office Ordinance, and it is also necessary to satisfy the requirements of the Supervision Guidelines and the Association's Self-regulatory Rules.